GeometricBrownianMotion
Systems / SDEs / Noise-driven systems
Multiplicative noise — the log-normal process underlying Black–Scholes and population growth under uncertainty.
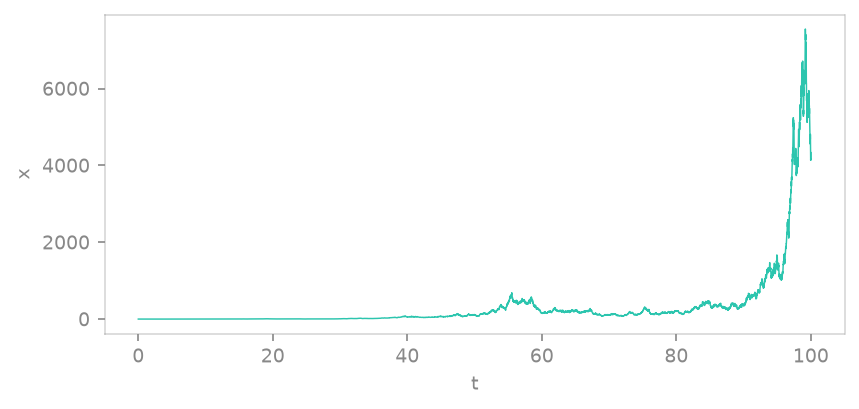
Definition
\[
\begin{aligned}
dx &= \left(\mu x\right)\,dt + \left(\sigma x\right)\,dW_{x}
\end{aligned}
\]
Parameters
| Symbol | Default | Role |
|---|---|---|
mu |
0.1 |
drift rate |
sigma |
0.3 |
volatility |
State variables: x
Properties
Lyapunov spectrum
TODO — SDE Lyapunov not computed at build time
Kaplan–Yorke dimension
TODO — requires a numeric Lyapunov spectrum
Divergence ∇·f
$\nabla\!\cdot f = \mu$
constant
constant
Equilibria
TODO — equilibria of a stochastic system not enumerated
Use it in TSDynamics
import tsdynamics as ts

system = ts.systems.GeometricBrownianMotion()
traj = system.run(final_time=100.0, dt=0.01)
ts.plot(traj)
Reference
Osborne (1959), Oper. Res. 7, 145-173
doi:10.1287/opre.7.2.145